01
UNDERSTAND RISK
Detect new risk categories, changing behaviour and connected exposure sooner.
Industries · Insurance & Risk
As products, infrastructure and behaviour change, exposure changes too. The keynote connects underwriting, claims, prevention and distribution to the emerging risk landscape.
Begin with your audience
Insurers, reinsurers, brokers, risk managers and insurance associations.
As products, infrastructure and behaviour change, exposure changes too. The keynote connects underwriting, claims, prevention and distribution to the emerging risk landscape. The final emphasis depends on who is attending, what they already understand, and the strategic choices your event is intended to support.
The research lens
These themes provide a direction for research, rather than a fixed set of slides. A leadership session can examine assumptions and investment priorities in depth. An industry conference can build a shared view of the changes affecting its members. A customer event can explore the future of the markets your customers serve.
From the industry brief
The sample guide develops five connected movements. The emphasis and examples are refined around the actual audience and event objectives.
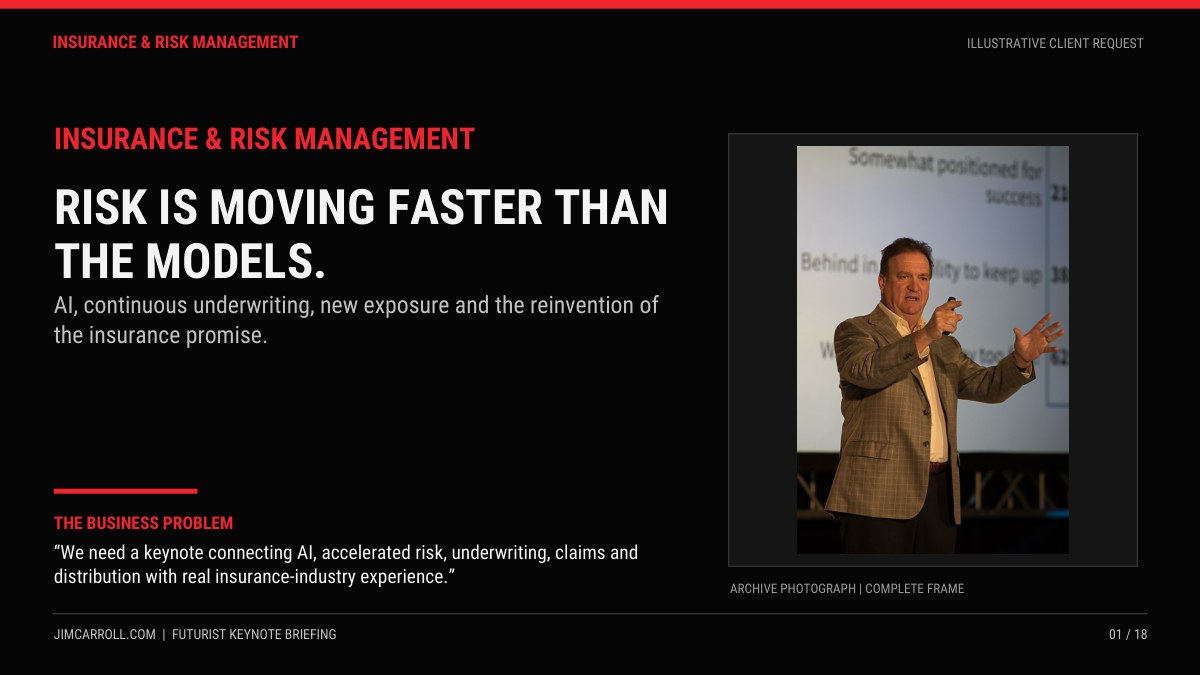
Illustrative industry brief · 18 pages
The complete guide develops the client challenge, relevant forces of change, keynote direction and industry experience. It is an illustrative briefing scenario, not a quotation from an actual client inquiry; the live proposal is shaped around your audience, priorities and objectives.
Read the insurance & risk brief (PDF) ↗All 21 briefs ↗Documented insurance & risk engagements
Selected clients
A sampling of the insurers, reinsurers and risk organizations Jim has worked with.
Global insurance leadership
Jim has addressed major carriers, associations and closed-door executive groups throughout the global insurance industry.
The published record
Relevant published engagements from JimCarroll.com. Cross-industry examples show adjacent markets and questions; the specific scope of each assignment is described in its original story.
The deep dive
From pricing the past to architecting risk.
For more than three decades, Jim Carroll has helped insurers, reinsurers, brokers, actuaries, benefits organizations and corporate risk leaders understand what happens when the velocity and complexity of risk change faster than the industry built to manage it.
The structural shift
Insurance spent centuries pricing the past. The industry now has to price the present, anticipate what comes next and increasingly prevent risk before it becomes a loss.
01
Detect new risk categories, changing behaviour and connected exposure sooner.
02
Move from historic averages toward predictive signals, continuous monitoring and intervention.
03
Build agility, insight and execution into an industry where the assumptions underneath the model keep changing.
Executive & insurance leadership
Technology changes underwriting and claims. Leadership determines whether the organization can change with them.
Jim has worked with insurance CEOs, CIOs, COOs, actuaries, distribution leaders, brokers and corporate risk executives for decades. The leadership question is not merely what is changing. It is what must we do differently because risk, technology and customer expectations are changing?
Agility. Insight. Execution.
Potential keynote directions
These are not canned speeches. They are possible directions selected and blended around the insurance segment, leadership team, audience and strategic issues in the room.
01
From pricing the past to architecting risk.
02
Underwriting, claims and risk in the intelligent era.
03
When risk accelerates faster than the models built to understand it.
04
From historical actuarial models to continuous risk assessment.
05
Reinventing human value in a direct, digital world.
06
Agility, insight and execution for insurance leadership.
Insurance transformation
Five strategic lenses for understanding what real-time information, AI and connected risk do to the insurance business model.
See emerging exposure and loss patterns earlier.
Use current, granular and behavioural data.
Intervene before risk becomes a claim.
Build products around real context and behaviour.
Become a risk-management partner, not merely a claims payer.
Predict & prevent
Connected risk turns insurance into an ongoing service.
Homes, vehicles, industrial assets, buildings, health devices and cyber systems increasingly report conditions continuously. That creates the opportunity to identify risk earlier, intervene sooner and potentially prevent loss altogether.
The claim you prevent may be more valuable than the claim you process faster.
AI & underwriting
Underwriting increasingly moves from static snapshots toward continuous risk signals and AI-assisted decisions.
Combine traditional data with current behavioural, spatial and connected-device information.
Accelerate routine decisions while escalating exceptions to human judgement.
Reassess exposure as conditions change rather than only at renewal.
Blend geography with property, crime, climate, infrastructure and community data.
Identify concentration and emerging exposure earlier across a book of business.
Use AI to increase speed and pattern recognition without abandoning judgement or governance.
Claims + fraud
But as AI gets better at creating evidence, insurance must get better at validating reality.
AI and connected data can automate first notice of loss, image-based damage assessment, triage, fraud analytics, straight-through processing and catastrophe response.
Deepfake imagery, synthetic identity, generated documentation and automated fraud operations create a new AI-versus-AI contest.
Accelerated risk
Risk appears faster, spreads faster, compounds faster and invalidates models faster.
Wildfire, flood, hurricane, heat and rebuilding costs challenge assumptions about property risk.
Adaptive threats turn cyber from a technology issue into financial, operational and physical risk.
AI liability, autonomous systems, synthetic biology, quantum risk and new energy systems create categories that may not yet fit existing models.
Usage-based insurance
Behaviour becomes a risk signal.
Jim was describing telematics-driven auto insurance years before usage-based insurance became mainstream. The same idea now extends to commercial fleets, equipment, health behaviour and temporary or contextual coverage.
Price the risk that exists, not merely the category it belongs to.
Life & health
Jim was describing performance-oriented insurance and bio-connectivity long before they became mainstream industry themes.
Wearables, health records, wellness data, predictive health, accelerated underwriting and longevity science increasingly connect insurance to measurable behaviour and changing health status.
Distribution disruption
Digital channels expose where human value really exists.
Digital simplicity resets expectations for buying, servicing and changing insurance.
The policy disappears into the car, trip, payment, device, home or platform.
Complexity, advice, advocacy, specialization and relationship become more valuable as routine transactions become digital.
Talent & actuarial science
Insurance expertise gets more specialized at exactly the moment the underlying risk environment becomes more complex.
Translate environmental change into exposure and pricing insight.
Price threats that evolve continuously and strategically.
Understand algorithmic liability, governance and model risk.
Build products around measurable triggers rather than traditional claims processes.
Experience
Jim's insurance work predates insurtech, AI underwriting and the connected-device economy.
1990s
Internet disruption, online distribution, privacy, security and changing broker relationships.
2000s
Technological risk, underwriting complexity, customer empowerment and agility.
2010s
Telematics, bio-connectivity, predictive analytics, usage-based products and insurtech.
2020s
Automated underwriting, cyber, climate, fraud, embedded insurance and real-time risk data.
2030s
Insurance evolves from transferring risk toward helping clients anticipate, reduce and manage it continuously.
The prediction scorecard
A useful futurist leaves receipts.
2009
Faster science and change would create new niche skills and harder risk assessment.
2011
Auto insurance would increasingly price actual driving behaviour.
2014
Measurable wellness behaviour would influence insurance economics.
2015
Wearables and health data would reshape life underwriting and engagement.
2016
Predictive analytics would push the industry toward real-time coverage.
2023+
AI would accelerate underwriting, claims, fraud analysis and the emergence of new risk itself.
Client stories
Life insurance, P&C, reinsurance, risk management and industry leadership require very different future stories.
New York Life
Data, digital distribution, changing buyers and the future of financial protection.
Zurich
Accelerated risk, AI, post-pandemic volatility and the leadership challenge of managing uncertainty.
LIMRA
Life insurance, insurtech disruption, trust, distribution and evolving customer expectations.
Insurance C-Suite
Private leadership discussions with senior executives across major global carriers on future risk, underwriting and disruption.
Risk Leadership
How insurers can become broader risk partners as complexity and connectivity accelerate.
Insurance Associations
Property/casualty, life, brokers, actuarial, benefits and reinsurance audiences across decades of industry change.
Deep customization
Because a life insurance CEO does not need the same future as a P&C underwriter, reinsurer, broker or benefits organization.
Client calls, market reports, regulatory and technology analysis, current news, audience issues and segment-specific examples. Jim's existing insurance site notes that his broader research process can involve accessing thousands of highly relevant articles and reports.
LISTEN → RESEARCH → MAP THE RISKS → BUILD THE STORY → CONNECT THE ROOM → LEAVE A PLAYBOOK
These sections come from insurance.jimcarroll.com, Jim’s insurance industry site, migrated here with their original copy and images.
From the research archive
Other industries
Make it about your audience
Bring the event objectives, the people attending and the questions you want them discussing afterward.